Phone:

(949) 432-4805

Address:

25 Mauchly, Suite 309 Irvine Ca 92618

Contractor Insurance Questions

California Contractor Insurance FAQs

Find clear answers to common contractor insurance questions in California, including general liability, workers’ compensation, builders risk insurance, contractor bonds, coverage requirements, certificates of insurance and more.

What Is Contractor Insurance?

Contractor insurance refers to a combination of insurance policies and surety bonds that can help protect contractors from financial risks associated with construction work. Depending on the contractor’s trade, employees, project requirements and contracts, coverage may include general liability insurance, workers’ compensation, builders risk and other specialized policies.

In California, insurance and bonding needs can vary by license classification and the type of work being performed. Some requirements may come from state law or CSLB rules, while others may be required by project owners, general contractors, lenders or construction contracts.

This FAQ resource answers common questions California contractors have when evaluating coverage, certificates of insurance and surety bond requirements.
Contractor Insurance

Contractor Insurance Coverage at a Glance

Contractor insurance is not a single policy. Contractors may need a combination of coverage based on their business operations, employees and projects.

In California, insurance and bonding needs can vary by license classification and the type of work being performed. Some requirements may come from state law or CSLB rules, while others may be required by project owners, general contractors, lenders or construction contracts.

This FAQ resource answers common questions California contractors have when evaluating coverage, certificates of insurance and surety bond requirements.

General Liability Insurance

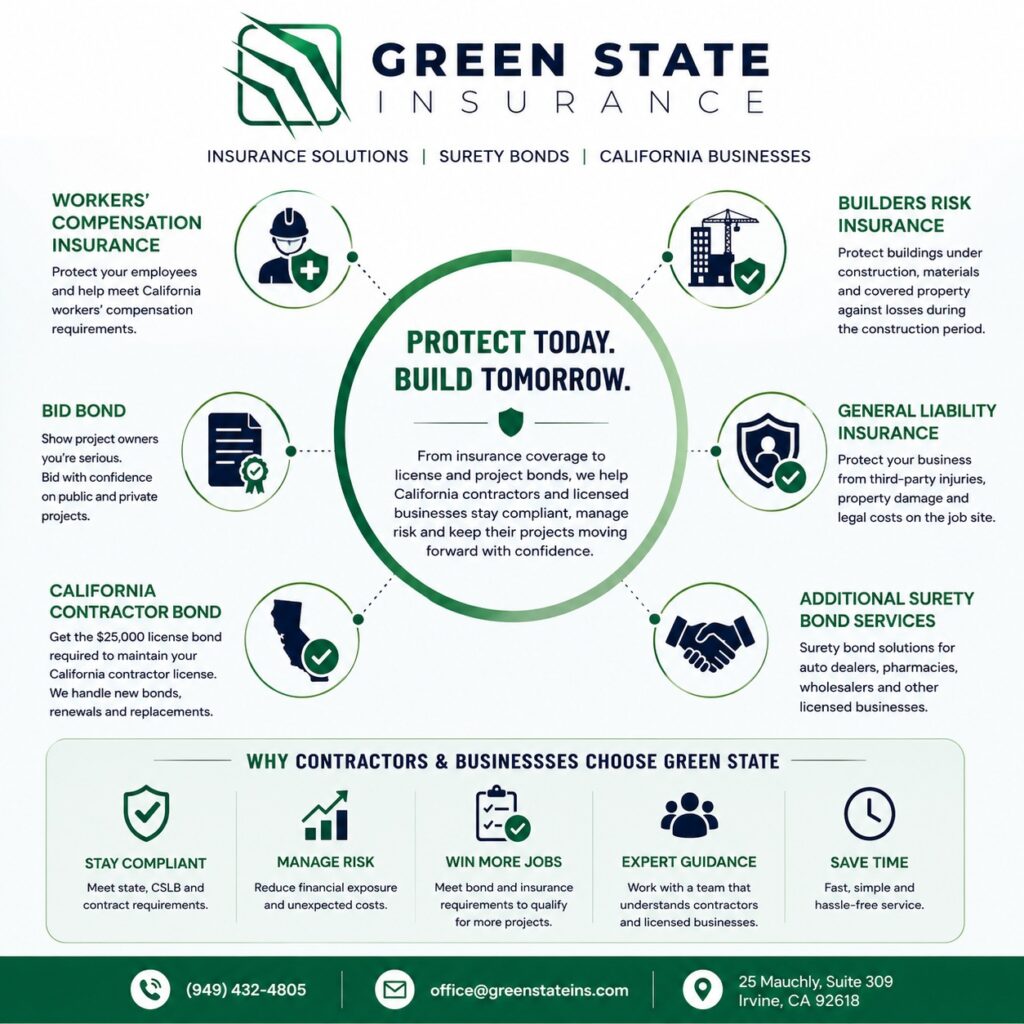
Helps protect contractors against covered third-party bodily injury, property damage and certain liability claims arising from business operations.

Workers’ Compensation

Provides benefits for qualifying work-related employee injuries or illnesses and may be required for California contractors depending on applicable rules and circumstances.

Builders Risk Insurance

Helps protect buildings under construction, materials and covered property against qualifying losses during an active construction project.

Surety Bonds

Contractor license bonds and project-specific bonds may be required for licensing, bidding or performing certain construction contracts.
Licensing & CSLB Requirements

CSLB contractor insurance refers to the required coverage — including a surety bond and liability insurance — needed to comply with California State License Board regulations. Most California contractor license classifications require a $25,000 surety bond plus general liability insurance to remain licensed and legally operate on job sites.
Yes. In California, most contractor license classifications require a $25,000 surety bond to meet CSLB licensing requirements. This bond protects consumers if a contractor fails to complete a project or violates licensing laws. Without an active bond on file with the CSLB, your license can be suspended. Green State Insurance can assist with new bonds, renewals, and replacement bond applications.
Yes. Green State Insurance provides contractor insurance for all California CSLB license types — from Class A General Engineering and Class B General Building contractors to all specialty C-license classifications including electrical, plumbing, HVAC, roofing, concrete, and painting. View our contractor insurance options to find coverage tailored to your license type.
Yes. In California, any contractor with one or more employees is legally required to carry workers’ compensation insurance under California Labor Code Section 3700. It covers medical expenses and lost wages if an employee is injured on the job. Operating without workers’ comp can result in fines, stop-work orders, and even criminal penalties. Learn more about Workers’ Compensation Insurance at Green State Insurance.
A lapse in contractor insurance or your CSLB surety bond can have serious consequences: the CSLB can suspend your contractor license, you may be prohibited from working on active projects, project owners can terminate your contracts, and future premiums may increase. Green State Insurance sends renewal reminders to help you avoid coverage gaps. Contact us to renew your contractor bond.

Cost & Process

The cost of contractor insurance in California depends on your trade (plumbing, electrical, concrete, roofing, etc.), business size, annual revenue, number of employees, and coverage needs. General liability for a small contractor can start around $500 to $1,500 per year. Workers’ comp rates vary by payroll and classification code. CSLB bonds start at low annual premiums depending on credit. Contact Green State Insurance for a personalized quote.
With Green State Insurance’s streamlined process, you can often receive a personalized contractor insurance quote within the same business day after providing the required details. For CSLB surety bonds, approval can be even faster — sometimes within hours — depending on the bond type and your credit profile.
To prepare an accurate contractor insurance quote in California, we typically need: your business name and license number, CSLB license classification, number of employees and subcontractors, types of projects you work on, annual revenue, and desired coverage limits. Having this information ready speeds up the quoting process significantly. Contact us to get started.
Yes. Green State Insurance works with both new startups and established businesses to find competitive rates on general liability, workers’ compensation, and builders risk insurance. Pricing depends on your trade type, annual revenue, number of employees, and claims history. We tailor coverage packages to match your budget without sacrificing required protection.
Yes. Green State Insurance offers flexible monthly payment options to make contractor insurance more affordable. Rather than paying the full annual premium upfront, eligible policyholders can spread payments throughout the year. Payment plans are available for general liability, workers’ compensation, and other commercial insurance products.
In most cases, contractor insurance premiums are considered an ordinary and necessary business expense and are tax-deductible under IRS rules. This includes general liability, workers’ compensation, and commercial auto insurance premiums. Consult your tax advisor to confirm deductibility for your specific situation.
We recommend reviewing your contractor insurance annually at renewal or after any major business changes — such as hiring new employees, taking on larger projects, purchasing new equipment, or expanding into new trade types. Coverage needs change as your business grows, and an outdated policy may leave you underinsured. Contact Green State Insurance to review your current coverage.

Coverage Types

Green State Insurance offers a full range of contractor insurance solutions in California, including: General Liability Insurance, Workers’ Compensation Insurance, Builders Risk Insurance, CSLB Contractor Surety Bonds, Bid Bonds, Auto Dealer Bonds, and Pharmacy Bonds. All products are tailored for California contractors, specialty trades, and regulated industries.
General liability insurance protects California contractors from third-party claims for bodily injury, property damage, or personal injury that may occur during business operations. If a client is injured on a job site or their property is damaged during your work, general liability covers legal defense costs and settlements. It also includes completed operations coverage for claims that arise after a project is finished.
Builders risk insurance covers buildings under construction against risks like fire, theft, vandalism, lightning, and certain weather-related damage until the project is completed. Coverage can be structured around the project type, construction value, location, and expected completion timeline. California contractors in trades such as framing, drywall, roofing, and tile rely on this coverage to protect work-in-progress and materials across job sites.
Workers’ compensation insurance for California contractors covers medical treatment, temporary and permanent disability benefits, and lost wages for employees injured on the job. It also covers death benefits for dependents in fatal workplace accidents. Coverage may be required based on your number of employees, license classification, and current CSLB rules. California law requires all employers — including contractors — to carry workers’ comp as soon as they hire their first employee.
A bid bond is required when bidding on eligible public and private construction projects. It is designed to support contract requirements and demonstrate your ability to enter the contract if selected. If you win the bid and fail to sign the contract, the bond compensates the project owner. Bid bonds are commonly required on California public works projects and larger private commercial contracts.
Standard general liability insurance does not typically cover tools and equipment. That is covered under a separate Inland Marine or Equipment policy, sometimes called tools and equipment coverage. Some business owner policies (BOP) can include or add this coverage. If your tools are stolen from a job site or vehicle, a standalone tools and equipment policy would respond.
Yes. Many general liability policies include completed operations coverage, which protects contractors from liability claims that arise even after a project is finished. For example, if a structure you built develops a defect that causes injury or damage months later, completed operations coverage can respond to that claim.
Yes. Contractors often bundle general liability with workers’ compensation, commercial auto, or umbrella coverage to save money and simplify policy management. Bundling can also make it easier to coordinate claims when multiple coverages are involved in the same incident.
Public project contracts in California often require higher liability limits (commonly $2 million or more per occurrence), bid bonds and performance bonds, payment bonds to protect subcontractors and suppliers, and additional insured endorsements naming the public agency. Green State Insurance can help structure coverage to meet these requirements.
Surety bonds provide a financial guarantee that your work will be completed according to contract terms. If a contractor fails to finish a project or causes financial harm, the bond provides compensation to the client up to the bond amount. In California, the CSLB requires a $25,000 contractor license bond specifically to protect consumers from contractor misconduct or abandonment.
Yes. Subcontractors in California should carry their own general liability and workers’ compensation insurance. General contractors typically require subcontractors to provide a Certificate of Insurance (COI) naming the GC as an additional insured before starting work. Without their own coverage, subcontractors expose themselves to serious financial risk and may be unable to secure work.
Yes. In addition to contractor bonds, Green State Insurance provides specialized surety bond solutions for other regulated California businesses. Auto dealer bonds help dealerships meet California licensing and renewal requirements. Pharmacy bonds are available for pharmacies, wholesalers, and related businesses that must meet applicable state, federal, or licensing requirements.

Winning More Work

Yes. Having valid contractors insurance demonstrates professionalism, financial stability, and compliance — giving clients and project owners confidence in your work. Many public and private construction contracts in California require proof of insurance (a Certificate of Insurance or COI) before award. A general liability policy and active CSLB bond help you qualify for more bids and larger contracts.
Project owners require a Certificate of Insurance (COI) to guarantee financial protection in case of accidents or damages on the job site. It confirms the contractor is covered and can pay for claims without the project owner bearing the cost. Most commercial and public contracts in California require specific minimum liability limits before work can begin. Green State Insurance can issue your COI quickly after binding coverage.
General contractor insurance typically covers larger-scale projects and the oversight of multiple trades, while subcontractor insurance focuses on specific tasks within a project. Both provide liability protection, but general contractors often need higher coverage limits and additional insured endorsements to list project owners. Subcontractors are usually required by GCs to carry their own liability and workers’ compensation policies before starting work.
Green State Insurance is a trusted provider based in Irvine, CA, serving contractors statewide — including Los Angeles, San Diego, Orange County, the Bay Area, Sacramento, and the Inland Empire. We offer General Liability, Workers’ Compensation, Builders Risk, and Surety Bonds — all tailored for California CSLB requirements. Contact us today for a same-day quote.
California Contractor Insurance

Explore Contractor Insurance and Bond Options

Running a contracting business means dealing with risks that can change from one job to the next. A job-site accident, property damage claim or employee injury can quickly become expensive without the right protection. General Liability Insurance can help protect against covered third-party injury and property damage claims, while Workers’ Compensation Insurance helps address qualifying work-related employee injuries and applicable California requirements.

Taking on a new construction project can create another concern: what happens if materials, supplies or the building itself are damaged before the work is finished? Builders Risk Insurance helps protect covered property during active construction. Contractors bidding on qualifying public or private projects may also need a Bid Bond to satisfy contract requirements and support their bid.

Licensing and bonding requirements can be just as important as insurance coverage. California contractors may need a $25,000 California Contractor Bond to maintain an active contractor license. Green State Insurance also assists regulated businesses with specialized surety solutions, including California Auto Dealer Bonds and Pharmacy Bonds for applicable licensing, renewal and regulatory requirements.

Contractor Insurance Support

Still Have Questions About Contractor Insurance?

Every contracting business is different. Green State Insurance can help you review your operations, project requirements and current coverage to identify insurance and surety options that fit your business.

Serving contractors across California with insurance and surety bond solutions.

Follow Green State Insurance