
Workers’ Compensation Insurance
Protect employees after work-related injuries or illnesses while helping your contracting business meet applicable California workers’ compensation requirements.
Explore Workers’ Compensation →
(949) 432-4805
25 Mauchly, Suite 309 Irvine Ca 92618
Contractor general liability insurance helps protect California construction businesses against eligible third-party bodily injury and accidental property damage claims arising from their operations. It can be important when working on residential, commercial or subcontracted projects where proof of liability coverage may be requested.
Commercial general liability insurance is not a blanket CSLB requirement for every California contractor. However, California contractor LLC licenses are subject to specific liability insurance requirements, and individual contracts or projects may require additional coverage or proof of insurance before work begins.
General liability insurance is designed to protect contractors from certain claims involving people or property outside their business. The exact protection depends on the policy, trade, exclusions and circumstances of the claim, but contractor policies commonly address several important liability exposures.
Helps protect your contracting business when a customer, visitor or another third party suffers a covered bodily injury connected to your operations. For example, a visitor could trip over equipment or construction materials at an active job site.
May cover qualifying accidental damage to property belonging to someone else. This could include damage to a customer's flooring, walls, fixtures or other property while your crew is performing covered construction or remodeling work.
General liability policies may also respond to certain covered personal and advertising injury claims, subject to policy terms and exclusions. These can include qualifying allegations related to advertising activities or other defined offenses.
When a covered liability claim results in a lawsuit, the policy may help pay eligible legal defense expenses and other covered costs. The scope of defense protection depends on the policy terms and circumstances of the claim.
Coverage may extend to qualifying bodily injury or property damage that occurs after contracted work has been completed. This protection can be especially important when a problem connected to completed construction work appears after the contractor has left the job site.
General liability insurance provides important protection, but it does not cover every risk a contracting business may face. Certain exposures require separate insurance, while others may be excluded by the terms of the policy.
Coverage note: Coverage, exclusions and endorsements vary by insurer, policy, contractor classification and individual risk. Always review the actual policy terms to determine what is and is not covered.
Work-related injuries or illnesses involving employees are generally handled through workers’ compensation insurance.
Liability or physical damage involving company vehicles typically requires commercial auto insurance.
Damage to or theft of contractor tools and equipment may require commercial property or inland marine coverage.
Claims involving professional advice, design services or certain errors and omissions may require separate professional liability coverage.
Commercial general liability policies commonly contain pollution exclusions, so specialized coverage may be needed for certain exposures.
Intentional injury or property damage is generally excluded from commercial general liability coverage.
Commercial general liability insurance is not a blanket CSLB requirement for every licensed contractor in California. However, certain business structures — particularly contractor LLCs — are subject to specific liability insurance requirements. General liability coverage may also be required by a project owner, general contractor or contract before work begins.
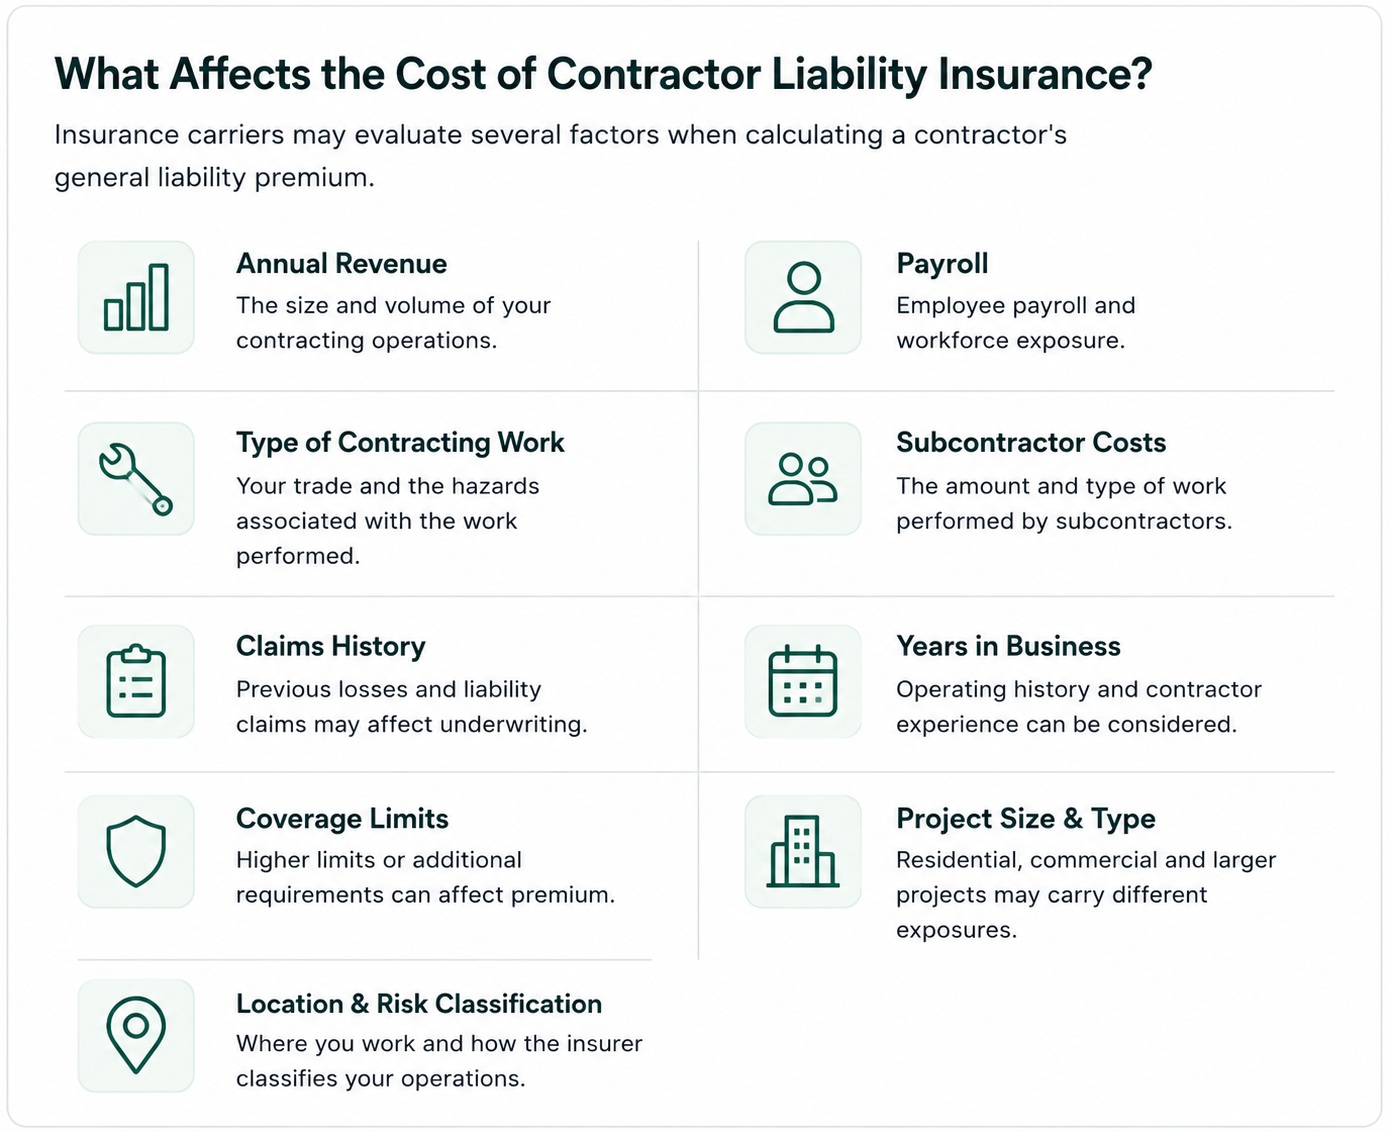
There is no single fixed price for contractor general liability insurance in California. Premiums are based on the individual characteristics of the contracting business and the level of risk associated with its operations.
A contractor performing lower-risk interior work may be evaluated differently from a roofing, demolition or other higher-risk construction business. Insurers can also consider revenue, payroll, subcontractor costs, claims history, requested coverage limits and other underwriting information when determining eligibility and premium.
Your actual premium depends on your trade, operations, limits and business-specific risk factors.
Contractors face different insurance requirements based on their trade, business structure and the projects they take on. Green State Insurance helps California contractors review coverage options, certificates and project-specific requirements with support focused on the construction industry.
Insurance options structured around your contracting operations and risk profile.
Help with certificates of insurance, additional insured requests and contract-specific coverage requirements.

A Certificate of Insurance provides a summary of your active coverage and is commonly requested as proof that required insurance is in place before contracted work begins.
A project owner, general contractor or another party may ask to be added as an additional insured for qualifying liability arising from your work, subject to policy and endorsement terms.
Contract terms may require specific coverage limits or endorsements depending on the project and the parties involved.
Need help meeting your project’s insurance requirements?
Start your application and provide your trade, project and coverage information so your insurance requirements can be reviewed.

General liability insurance can be important for contractors whose work creates potential third-party injury or property damage exposures. Coverage needs vary by trade, project type, business structure and contractual requirements.
California general contractors, subcontractors, remodelers and specialty trades may need liability coverage to meet client or project requirements and help protect their businesses from qualifying claims.
Common contractor trades include:
General Contractors · Electrical Contractors · Plumbing Contractors · HVAC Contractors · Roofing Contractors · Painting Contractors · Concrete Contractors · Flooring Contractors · Carpenters · Remodelers

Building across California? We’ve got your contracting risks covered. Request a free, no-obligation quote today for surety bonds, general liability, builders risk, bid & performance bonds, and workers’ compensation—everything a California contractor needs to stay compliant, competitive, and worry-free. Connect with our specialists now and lock in coverage you can build on.
General liability is one part of protecting and maintaining a contracting business. Explore additional insurance and bond solutions based on your employees, projects, licensing requirements and contractual obligations.
Protect employees after work-related injuries or illnesses while helping your contracting business meet applicable California workers’ compensation requirements.
Explore Workers’ Compensation →Protect buildings under construction, materials, supplies and other covered property against qualifying losses during an active construction project.
Explore Builders Risk →Bid on eligible public and private construction projects with a bond designed to support contract requirements.
Explore Bid Bonds →Get support securing the $25,000 contractor license bond required to maintain an active California contractor license.
Explore Contractor Bonds →Green State Insurance also provides specialized surety bond solutions for California auto dealers, pharmacies, wholesalers and other licensed businesses.
Get assistance with California auto dealer bond requirements for licensing, renewal and continued dealership operation.
Explore Auto Dealer Bonds →Access surety bond solutions for pharmacies, wholesalers and related businesses with applicable licensing or regulatory requirements.
Explore Pharmacy Bonds →