
Business Insurance California: Coverage That Fits Your Company’s Real Risks
Running a business comes with risks that can quickly turn into unexpected expenses. Business Insurance California coverage can help protect your company from losses involving liability claims, employee injuries, property damage, business vehicles, and other covered risks.
Whether you run a service company, retail business, professional office, contracting company, or growing small business in California, the right insurance should reflect how your company actually operates.
At Green State Insurance, we help business owners understand their risks, compare coverage options, and find business insurance California that fits their operations and requirements.
Business insurance helps protect your company from covered losses that could otherwise come directly out of your pocket. Whether you operate a service company, retail business, professional office, contracting company, or growing small business, your coverage should reflect how your business actually operates.
At Green State Insurance, we help California business owners understand their risks, compare coverage options, and find insurance that fits their operations, employees, property, vehicles, and contractual requirements.
| If You’re Concerned About… | Coverage to Consider |
|---|---|
| A customer gets injured at your business or job site | General Liability Insurance |
| Your business accidentally damages someone else’s property | General Liability Insurance |
| An employee gets hurt while working | Workers’ Compensation Insurance |
| Your equipment, inventory, or business property is damaged | Commercial Property Insurance |
| You or an employee uses a vehicle for business | Commercial Auto Insurance |
| A client or landlord asks for a Certificate of Insurance (COI) | General Liability Insurance |
| A client requires you to add them as an Additional Insured | General Liability Insurance |
| You provide professional advice or services and a client claims you made a mistake | Professional Liability Insurance |
| You want liability and property coverage in one policy | Business Owner’s Policy (BOP) |
| You’re a contractor who needs insurance to qualify for a project | Contractor Insurance & Bonds |
Choose the Right Business Insurance California Coverage
The first step is understanding what kind of protection your business needs.
A business structure like an LLC or corporation may help separate personal and business liability, but it does not replace insurance. That protection has limits. If your company faces a lawsuit, property damage claim, employee injury, or contract dispute, business insurance can help fill the gaps.
Some coverage may also be required by law, by a client contract, by a general contractor, by a landlord, or by a licensing agency.
For example, many California businesses need coverage such as:
General Liability Insurance
Helps protect against third-party bodily injury, property damage, and certain legal claims.
Workers’ Compensation Insurance
Required for California businesses with employees and important for protecting workers after job-related injuries.
Commercial Property Insurance
Helps protect business property, tools, equipment, inventory, furniture, and physical assets from covered losses.
Commercial Auto Insurance
Important for businesses that use vehicles for work, deliveries, jobsite visits, or transporting equipment.
Business Owner’s Policy / BOP
A package policy that can combine general liability and commercial property coverage for eligible small businesses.
Professional Liability Insurance
Useful for businesses that provide advice, consulting, design, professional services, or specialized expertise.
For contractors and trade businesses, coverage may also need to support COI requirements, subcontractor rules, jobsite risks, and project owner requirements.
Common Types of Business Insurance
Different businesses need different coverage. A flooring contractor, café, medical office, consultant, remodeler, or retail business may all need protection, but not always the same kind.
Here are some of the most common business insurance options Green State Insurance can help you review:
California Contractor Insurance & Bonds
Fast online quotes for general liability, workers’ compensation, builders risk insurance, contractor bonds, auto dealer bonds, and pharmacy bonds across California.
General Liability Insurance
Protect your contracting business from third-party injury claims, property damage, and unexpected job site risks across California.
Workers Compensation Insurance
Stay compliant with California labor laws while protecting your employees and subcontractors on every project.
Contractors Bond
Fast CSLB contractor bond approvals to help keep your license active and your business compliant in California.
Builders Risk Insurance
Protect construction projects, tools, materials, and job sites from unexpected losses during active construction.
Bid Bond
Submit projects with confidence using fast California bid bond solutions for public and private construction jobs.
Auto Dealer Bond
California auto dealer bond quotes designed to help dealerships stay licensed, compliant, and ready to operate.
Pharmacy Bond
Reliable California pharmacy bond solutions for wholesalers and businesses requiring state bond compliance.
Need a Fast Quote?
Speak with Green State Insurance and get help choosing the right contractor insurance or bond solution in California.
The right policy depends on what your business does, where it operates, whether you have employees, whether you use vehicles, and what your clients require before you can begin work.
General Liability Insurance
General Liability Insurance is one of the most important policies for many businesses.
It can help protect your company if someone claims your business caused bodily injury, property damage, or certain personal and advertising injury. For contractors, this can include damage to client property, jobsite accidents, or claims from property owners and general contractors.
Many clients and commercial projects will ask for a Certificate of Insurance, also called a COI, before allowing work to begin.
For many California contractors, this is not optional in practice. Without proof of general liability coverage, you may lose access to larger projects.
Workers’ Compensation Insurance
If your business has employees in California, workers’ compensation is usually required.
This coverage helps protect employees if they are injured while working. It can help pay for medical treatment, lost wages, and other job-related injury benefits.
For contractors, construction businesses, service companies, and businesses with physical labor, workers’ compensation is especially important. One workplace injury can quickly become expensive without proper coverage.
It can also affect your ability to qualify for projects, pass compliance checks, or work with larger clients.
Business Insurance for Contractors
Contractors face a different type of risk than many small businesses.
You work on someone else’s property. You use tools, vehicles, materials, subcontractors, and crews. You may be responsible for damage, delays, injuries, installation mistakes, or contract requirements.
Green State Insurance helps California contractors review coverage for:
- General contractors
- Flooring contractors
- Painters
- Roofers
- Plumbers
- Electricians
- HVAC contractors
- Concrete contractors
- Remodelers
- Cabinet installers
- Tile and flooring installers
- Handyman and specialty trades
Contractor insurance may include general liability, workers’ compensation, commercial auto, tools and equipment coverage, and surety bonds.
The goal is simple: protect the business while helping contractors meet jobsite, licensing, and COI requirements.
Business Insurance California: 5 Smart Ways to Protect Your Business
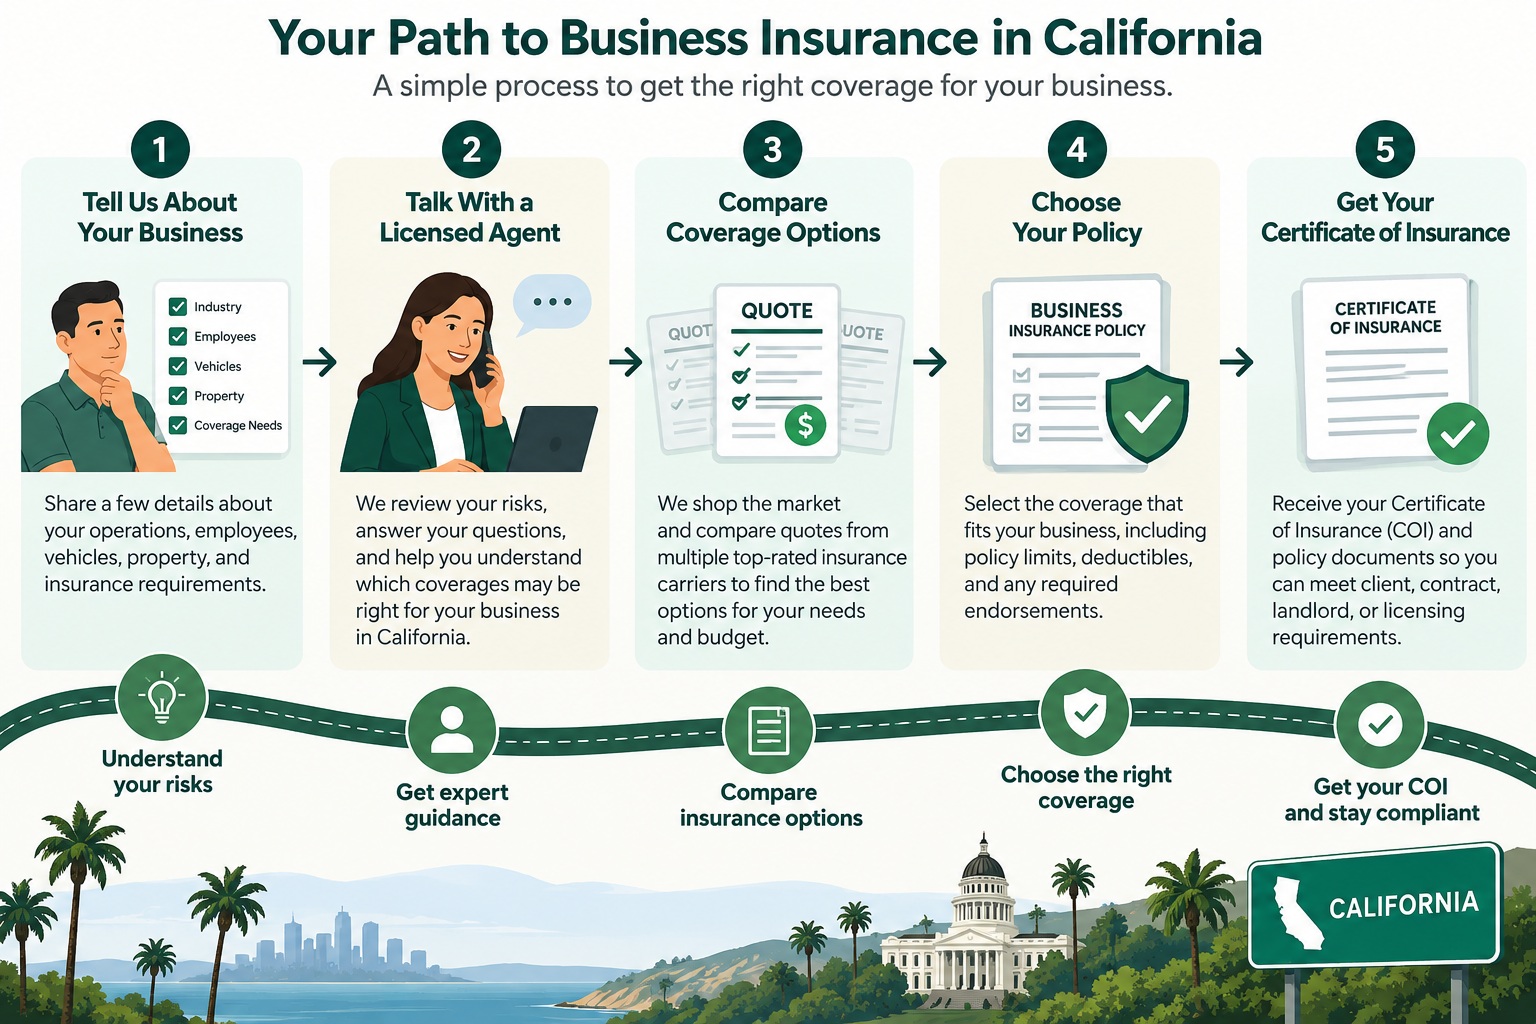
Getting business insurance California doesn’t have to be complicated. Start with a few details about your business, understand your risks, compare your options, and choose coverage that fits the way you actually operate.
1. Tell Us About Your Business
Start by sharing a few basic details about your company, including:
- Your industry and business activities
- Number of employees
- Payroll and annual revenue
- Business location
- Vehicles used for work
- Property, tools, or equipment
- Current insurance coverage
- Contract or COI requirements
These details help us understand your business and identify the risks that may need coverage.
2. Talk With a Licensed Insurance Agent
Next, speak with a licensed commercial insurance agent about your operations and coverage needs.
At Green State Insurance, we help California business owners understand which types of coverage may apply to their business, including general liability, workers’ compensation, commercial property, commercial auto, professional liability, and BOP coverage.
We can also review insurance requirements from clients, landlords, contracts, or other business obligations.
3. Compare Coverage Options
Once we understand your needs, you can compare available business insurance options in California.
Look beyond the premium and consider:
- Coverage limits
- Deductibles
- Exclusions
- Additional insured options
- COI requirements
- Required endorsements
- Property and equipment coverage
- Commercial auto needs
- Workers’ compensation requirements
The goal is to find coverage that fits both your business risks and your specific requirements.
4. Choose Your Business Insurance Policy
After reviewing your options, choose the policy and coverage limits that make sense for your business.
Before the policy is issued, make sure you understand what is covered, what is excluded, your deductible, policy limits, and any endorsements required by your clients or contracts.
Your California business insurance should reflect how your company actually operates—not simply be the cheapest policy available.
5. Get Your Certificate of Insurance
Once your policy is active, you can receive your policy documents and, when applicable, a Certificate of Insurance (COI).
A COI may be requested by:
- Clients
- Landlords
- General contractors
- Property managers
- Project owners
- Other parties requiring proof of coverage
As your company grows, review your insurance at renewal and after major changes such as hiring employees, adding vehicles, purchasing equipment, expanding services, or taking on larger contracts.
Your business changes. Your insurance should keep up.
When Do You Need a Certificate of Insurance?
A Certificate of Insurance is often requested by clients, landlords, general contractors, project owners, and property managers.
A COI shows proof that your business has active insurance coverage. It may include:
- General liability limits
- Workers’ compensation status
- Commercial auto coverage
- Policy dates
- Insurance carrier information
- Additional insured wording
- Waiver of subrogation, if required
For contractors and service businesses, COIs are often part of winning bigger jobs. If you cannot provide one quickly, you may delay the project or lose the opportunity.
Green State Insurance can help business owners handle COI requests more smoothly and make sure coverage lines up with project requirements.
“Commercial insurance can protect you from some of the most common losses experienced by business owners.”
Why Business Insurance California Coverage Matters
Business insurance is not only about preparing for the worst. It is also about staying eligible, professional, and ready for growth.
The right insurance can help your business:
- Protect against lawsuits
- Cover certain property damage claims
- Meet legal requirements
- Qualify for contracts
- Provide COIs to clients
- Protect employees
- Support business continuity
- Build trust with customers and project owners
Accidents happen. Claims happen. Contract requirements happen. Insurance gives your business a stronger foundation when the unexpected shows up.
How Green State Insurance Can Help
Finding the right Business Insurance California coverage starts with understanding your company’s actual risks, requirements, and day-to-day operations. Green State Insurance helps California businesses find coverage that fits their needs, budget, and risk level.
Whether you are starting a new business, renewing coverage, or trying to meet a contract requirement, our team can help you understand your options and move forward with confidence.
Business Insurance California FAQs
Common questions about Business Insurance California, coverage options, general liability, workers’ compensation, and protecting your company as it grows.