Compliance Issues with Contractor: 7 Warning Signs in California
Contractor compliance problems can affect much more than a construction schedule. In California, licensing, insurance, bonding, employee coverage, contract requirements, safety documentation, and certificates of insurance can all create problems when they are overlooked.
Some compliance issues with contractor businesses are easy to identify, such as an expired license or missing bond. Others may not become obvious until a general contractor requests updated insurance documents, a project requires additional coverage, or a claim occurs.
This guide covers common contractor compliance issues, warning signs to watch for, and the insurance and bonding requirements California contractors should review before they create problems for a project or business.
ontractor Compliance Issues: What Should You Check First?
Not sure whether your contractor business has a compliance gap? Start with the issue you’re facing and review the insurance, bond, or documentation that may need attention.
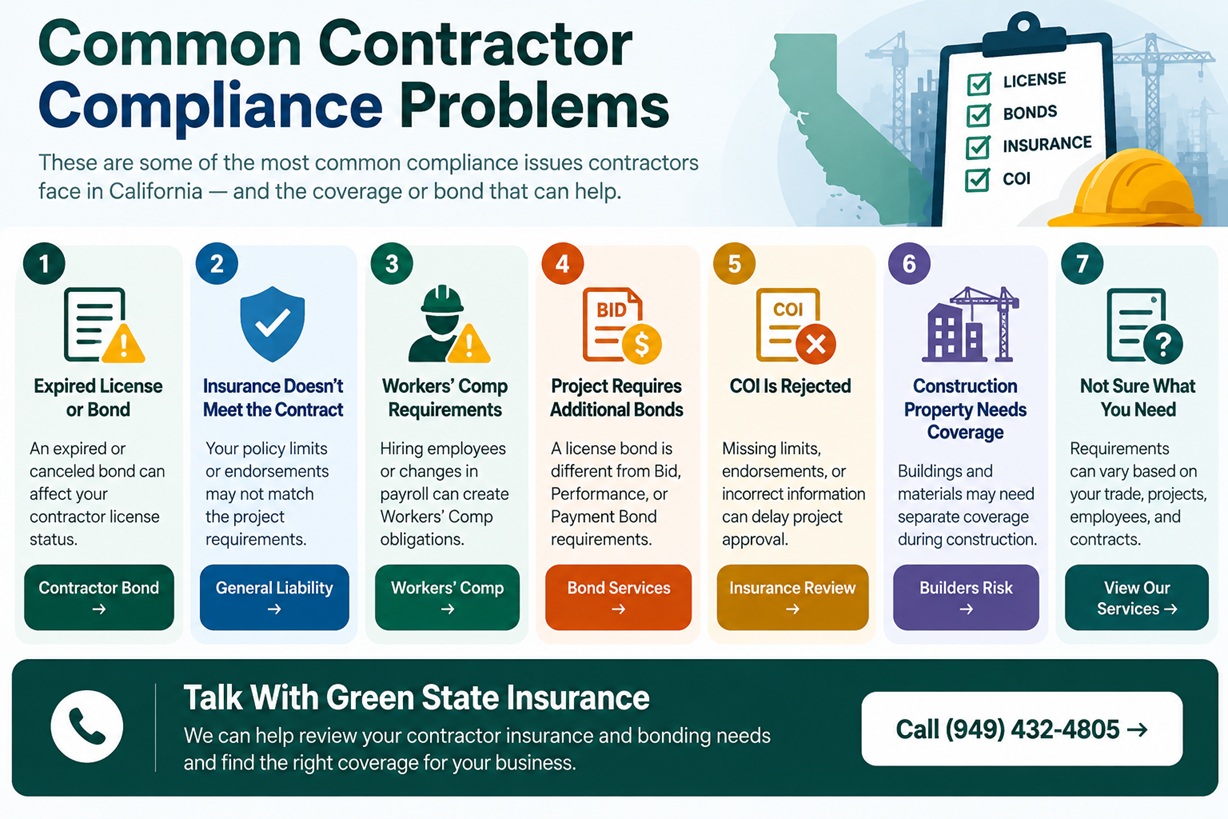
| If This Is Your Concern | What You Should Review | Green State Service |
|---|---|---|
| My GC says my liability insurance doesn’t meet the contract. | Review required limits, coverage, and applicable insurance provisions before work begins. | General Liability → |
| I have employees and need to review Workers’ Comp. | Review your current coverage, payroll, employee classifications, and applicable California requirements. | Workers’ Comp → |
| My contractor bond is missing, canceled, or needs renewal. | Check your applicable contractor bond requirement and make sure your bond information is current. | Contractor Bond → |
| My bid or construction contract requires a bond. | A license bond is different from project-specific Bid, Performance, or Payment Bond requirements. | Bond Services → |
| My COI was rejected or doesn’t match the project requirements. | Compare the contract requirements with your policies, limits, and requested insurance documentation. | Liability Coverage → |
| I need coverage for a building or materials during construction. | General Liability does not replace property coverage for buildings and materials during construction. | Builders Risk → |
| I’m not sure what insurance or bond my business needs. | Review your trade, employees, operations, license requirements, and construction contracts together. | View Our Services → |
Green State Insurance can help review your contractor insurance and bonding needs.
Call (949) 432-4805 →
What Are Compliance Issues With Contractor Businesses?
Contractor compliance issues occur when a contractor fails to satisfy an applicable licensing, contractual, insurance, bonding, employment, documentation, or project requirement.
Not every compliance problem means a contractor intentionally violated a rule.
Sometimes the problem is as simple as an expired document, an insurance policy that does not match a new contract, incorrect business information on a bond, or a new scope of work that was never reviewed with the insurance carrier.
The important part is identifying these issues before they delay a project, affect a license, or contribute to an uninsured or underinsured loss.
1. Contractor License or Bond Problems
One of the first areas California contractors should review is their license and applicable bond requirements.
California contractors generally need the applicable Contractor’s Bond in place to maintain an active license, and the standard Contractor’s Bond amount is currently $25,000.
Problems can arise when:
- A bond expires or is canceled.
- Business information doesn’t match licensing records.
- A qualifier requires an additional bond.
- A contractor assumes the $25,000 license bond covers project-specific bonding requirements.
For contractors who need the standard license bond:
→ California $25,000 Contractor Bond
2. General Liability Doesn’t Match the Contract
Having General Liability insurance doesn’t automatically mean your policy satisfies every construction contract.
A general contractor, property owner, or project agreement may require specific:
limits, Additional Insured status, Primary & Non-Contributory wording, Waiver of Subrogation, or other insurance provisions.
Problems often appear when the contractor submits a Certificate of Insurance and the certificate or underlying policy doesn’t satisfy the contractual requirements.
That can delay:
project approval → site access → payment → or commencement of work.
Before starting a new project, contractors should compare the insurance section of the contract with their actual policy.
3. Workers’ Compensation Compliance Issues
Workers’ Compensation is another major compliance area for California construction businesses.
A contractor’s obligations can change when employees are hired, payroll changes, classifications change, or business operations expand.
Common problems include incorrect payroll information, incorrect employee classifications, lapses in coverage, or assuming a contractor qualifies for an exemption when the applicable requirements say otherwise.
Green State Insurance can help contractors review Workers’ Compensation options based on their business operations and workforce.
→ Workers’ Compensation Insurance
4. Missing Project-Specific Bonds
This is where we connect directly to the previous article.
A contractor can have the required $25,000 California Contractor License Bond and still fail a project’s bonding requirements.
Why?
Because a license bond is not the same thing as:
Bid Bond
May be required when submitting a bid.
Performance Bond
May be required after the contractor is awarded the project.
Payment Bond
May be required to address certain payment obligations involving labor and materials.
If a bid package or construction contract contains bonding requirements, contractors should review them before the deadline rather than assuming their existing license bond is enough.
5. Certificate of Insurance Problems
A Certificate of Insurance—or COI—is one of the places where insurance compliance problems often become visible.
For example, a general contractor may request proof of:
- General Liability
- Workers’ Compensation
- Commercial Auto
- Umbrella/Excess Liability
- Specific policy limits
- Additional Insured status
- Other contract-required provisions
Simply having a COI does not mean every requirement in the construction contract has been satisfied.
The policy and requested endorsements need to be reviewed against the actual contract requirements.
6. New Work That Wasn’t Disclosed to the Insurer
Construction businesses evolve.
An electrical contractor may begin performing EV charger installations. A general contractor may take on larger commercial projects. Another business may begin using subcontractors or move into a different type of construction work.
Those changes should not automatically be assumed to fall within existing coverage.
When operations materially change, contractors should disclose the new activities and confirm how the policy responds.
This is particularly important when the new work changes the contractor’s risk profile.
7. Poor Documentation and Contract Management
Poor documentation is another warning sign of potential contractor non-compliance.
The competitor article specifically identifies missing documents, inconsistent reporting, failure to update records, and difficulty providing required records during audits or evaluations as potential warning signs. Simple But Needed
For a construction business, important records can include contracts, change orders, insurance documents, COIs, endorsements, payroll records, subcontractor documentation, bond documents, and project correspondence.
Good documentation doesn’t replace insurance or compliance requirements—but it can make those requirements much easier to verify and manage.
Warning Signs of Contractor Non-Compliance
| Warning Sign | What to Review |
|---|---|
| Repeated project delays | Contract obligations and project documentation |
| Missing or expired COIs | Current insurance policies |
| Bond cancellation or expiration | Contractor bond status |
| New employees without coverage review | Workers’ Compensation |
| Contract requires endorsements you don’t have | General Liability policy |
| New construction activities | Policy classifications and exclusions |
| Bid requires bonding | Bid/Performance/Payment Bond requirements |
| Missing project documentation | Record-keeping procedures |
SBN’s article also identifies repeated delays, inconsistent quality, communication problems, failure to follow contractual obligations, and inadequate record keeping as potential indicators of contractor non-compliance. Simple But Needed
Contractor Compliance Isn’t Just About Having Insurance
A common mistake is asking:
“Do I have insurance?”
when the better question is:
“Does my current insurance and bonding program match what my business and this project require?”
A contractor may have General Liability but insufficient contract-required limits.
They may have a Contractor License Bond but need a Performance Bond.
They may have Workers’ Compensation but have changed payroll or operations.
Or they may have a COI that doesn’t reflect a contract requirement.
That’s why compliance should be reviewed whenever there is a meaningful change in your business, workforce, operations, or project requirements.
Insurance and Bonds California Contractors Should Review
General Liability Insurance
Review third-party bodily injury and property damage coverage, policy limits, and applicable contract requirements.
Workers’ Compensation
Review employee coverage, payroll, classifications, and applicable California requirements.
Contractor License Bond
Confirm your applicable California contractor bond requirement and current bond status.
Builders Risk Insurance
Review property coverage when buildings and materials are exposed during construction.
How to Reduce Contractor Compliance Problems
A simple five-step review can help identify insurance, bonding, and contract issues before they delay your project.
Review Your License and Bond
Confirm your contractor license and applicable bond requirements are current.
Review Your Insurance Policies
Check General Liability, Workers’ Compensation, Auto, Umbrella, and other applicable coverage.
Read New Contract Requirements
Review the insurance section before work begins. Don’t wait until the GC rejects your COI.
Report Changes in Operations
New employees, services, subcontractors, vehicles, locations, and project types can change your insurance needs.
Review Before Starting Work
Resolve missing bonds, insurance requirements, or endorsements before they delay the project.
Need Help Reviewing Your Contractor Coverage?
Green State Insurance can help review your insurance and bonding needs before your next project begins.
Review Your Contractor Insurance and Bond Requirements
Contractor compliance is easier to manage before a project starts than after a missing bond, rejected COI, or insurance issue causes a delay.
Green State Insurance helps California contractors review insurance and bonding needs based on their operations and project requirements.
Whether you need General Liability, Workers’ Compensation, a California Contractor Bond, Builders Risk, or help understanding a project’s insurance requirements, start by reviewing what your business actually needs.
Call Green State Insurance: (949) 432-4805
→ View Contractor Insurance & Bond Services
Frequently Asked Questions About Contractor Compliance Issues
Quick answers to common questions about contractor compliance, insurance, bonds, and project requirements.
What are common compliance issues with contractor businesses?
Common issues can involve contractor licensing, bonds, insurance requirements, Workers’ Compensation, COIs, contract requirements, project-specific bonds, documentation, and changes in business operations.
Can a contractor have insurance and still be non-compliant?
Yes. Simply having an insurance policy does not mean it satisfies every licensing or contractual requirement. Policy limits, endorsements, classifications, and other terms may need to match specific requirements.
Does a California contractor need a $25,000 bond?
California’s standard Contractor’s Bond is currently $25,000 for an active contractor license, subject to applicable CSLB requirements.
Is a contractor bond the same as General Liability insurance?
No. A contractor bond and General Liability insurance serve different purposes. One does not automatically replace the other.
Why would a contractor’s COI be rejected?
Possible reasons include insufficient limits, missing required coverage, missing endorsements, incorrect information, or requirements in the contract that the submitted insurance documents do not satisfy.
Does a contractor license bond cover performance requirements?
No. A California Contractor License Bond is different from a project-specific Performance Bond.
Should contractors review insurance when their business changes?
Yes. Significant changes such as adding employees, services, vehicles, subcontractors, or different types of projects should be disclosed and reviewed because they may affect coverage or underwriting.
Have Questions About Your Contractor Insurance or Bond Requirements?
Talk with Green State Insurance about your California contractor coverage and bonding needs.