
High Mod Businesses Insurance: Workers’ Comp Options in California
Finding high mod businesses insurance can be challenging when your company has a higher Workers’ Compensation Experience Modification, often called an X-Mod or experience mod.
A high mod does not automatically mean your business cannot get insurance. However, it can affect how insurers evaluate your Workers’ Compensation risk, especially when your business has a history of workplace claims, higher claim costs, or operates in a higher-risk industry.
For California businesses, maintaining the right coverage is particularly important. California employers with one or more employees generally must maintain Workers’ Compensation coverage or qualify to self-insure.
High Mod Businesses Insurance: Start With Your Biggest Concern
A high Workers’ Comp mod can affect more than your premium. Start with the issue your business is facing and review the coverage or insurance service that may apply.
| Your Concern | What You Should Review | Green State Service |
|---|---|---|
| My Workers’ Comp mod is high and I need coverage. | Review your X-Mod, loss runs, payroll, employee classifications, claims history, and current Workers’ Comp policy. | Workers’ Comp → |
| My Workers’ Comp premium increased. | Review changes in your X-Mod, payroll, classifications, claims, and other factors affecting your current Workers’ Comp pricing. | Workers’ Comp → |
| I have open or previous Workers’ Comp claims. | Review current loss runs, claim status, significant losses, and the information contributing to your insurance risk profile. | Workers’ Comp → |
| A GC or project owner is asking for liability insurance. | Review General Liability coverage, required limits, project requirements, and the Certificate of Insurance requested by the contract. | General Liability → |
| I’m a contractor and also need my license bond. | Your Workers’ Comp coverage and contractor license bond serve different purposes. Review your applicable California contractor bond requirement separately. | Contractor Bond → |
| I’m starting a construction or renovation project. | Workers’ Comp does not replace coverage for buildings and certain property exposed during construction. Review the project’s property coverage needs. | Builders Risk → |
| I’m not sure what coverage my business needs. | Start with your operations, employees, payroll, claims history, contracts, and current insurance to identify the coverage areas that should be reviewed. | View Our Services → |
The key takeaway:
A high Workers’ Comp mod does not automatically mean your business is uninsurable. Your X-Mod is one part of a broader insurance profile that can include payroll, classifications, claims history, operations, and current coverage.
“What insurance options are available for my business, and what information will insurers review?”
Green State Insurance helps California businesses review Workers’ Compensation and other commercial insurance options based on their operations, payroll, classifications, claims history, and coverage requirements.
What Is a High Workers’ Comp Experience Mod?
An Experience Modification, or X-Mod, is part of the Workers’ Compensation experience rating system.
In California, the Workers’ Compensation Insurance Rating Bureau of California (WCIRB) calculates experience modifications for qualifying employers. WCIRB states that the experience rating worksheet uses audited payroll and losses for three consecutive policy periods. WCIRB
Your X-Mod provides insurers with information about your business’s historical Workers’ Compensation experience.
For example, insurers reviewing a business may consider factors such as:
| Factor | Why It Matters |
|---|---|
| Experience Modification | Helps evaluate historical Workers’ Comp experience |
| Claims History | Shows previous workplace losses |
| Claim Frequency | Multiple claims may indicate recurring exposure |
| Claim Severity | Large losses can affect the risk profile |
| Payroll | Used in Workers’ Comp rating |
| Employee Classifications | Different jobs have different workplace exposures |
| Business Operations | Helps determine the nature of the work being performed |
| Safety Practices | Can help insurers understand current risk controls |
WCIRB also provides an Experience Modification Estimator based on payroll, classifications and claims information, although estimates are not official WCIRB-published X-Mods. WCIRB
Why High Mod Businesses Can Be Harder to Insure
When searching for high mod businesses insurance, one of the biggest challenges is underwriting.
Workers’ Compensation carriers do not evaluate every business the same way.
A company with relatively straightforward operations and favorable loss experience may present a different underwriting profile than a contractor or other higher-risk employer with multiple claims or significant losses.
A high X-Mod can therefore lead to additional underwriting questions.
The insurer may want to understand:
What caused the claims?
Are the claims still open?
Have the business operations changed?
Has payroll increased or decreased?
Were the employee classifications accurate?
What safety improvements have been made?
Are there procedures for reporting and managing workplace injuries?
This is why simply shopping for the lowest Workers’ Compensation price may not address the underlying issue.
The complete risk profile matters.
Can a Business Get Workers’ Comp With a High Mod?
Yes, having a high Experience Modification does not by itself mean a business cannot obtain Workers’ Compensation insurance.
However, available options can depend on the individual risk.
Insurers may review your:
- X-Mod
- Loss runs
- Payroll
- Employee classifications
- Business operations
- Years in business
- Current and prior Workers’ Comp policies
- Open and closed claims
- Claim frequency and severity
- Safety procedures
For high mod businesses insurance, having accurate information available before requesting coverage can make the insurance review process more efficient.
It can also help identify issues that should be explained to an underwriter instead of allowing the X-Mod alone to tell the story.
Does a High Mod Increase Workers’ Compensation Cost?
A higher Experience Modification can affect Workers’ Compensation premium, but it should not be viewed as the only factor determining what a business will pay.
Workers’ Compensation pricing can also depend on payroll, employee classifications, industry, location, claims information and insurer-specific underwriting.
In California, WCIRB explains that the experience rating system uses payroll and loss information reported by insurers. WCIRB
This means two businesses with apparently similar operations may still receive different insurance pricing.
Simple Example
Imagine two contractors with similar payroll and employee classifications.
Contractor A
X-Mod: 0.85
Few recent losses
Stable operations
Contractor B
X-Mod: 1.35
Multiple prior claims
Several open claims
Their Workers’ Compensation insurance profiles can look very different to an insurer even if they perform similar work.
This example is illustrative only and is not a premium calculation.
What Causes a High Workers’ Comp Mod?
There is no single cause of a high Experience Modification.
Claims and payroll information play an important role in California’s experience rating system. WCIRB receives payroll and loss data by classification through insurer-submitted Unit Statistical Reports, and that data is used in administering the Experience Rating System. WCIRB
Potential factors can include frequent workplace injuries, significant claims, changes in payroll or workforce, and the historical loss information included in the applicable experience period.
For this reason, businesses should review the underlying information rather than focusing only on the final X-Mod number.
High Mod Businesses Insurance: What Coverage Should You Review?
Workers’ Compensation may be the primary concern for a company with a high X-Mod, but it may not be the only insurance the business needs.
1. Workers’ Compensation Insurance
Workers’ Compensation is the primary coverage associated with an Experience Modification.
For California employers, this is particularly important because businesses with employees generally must maintain Workers’ Compensation insurance or meet applicable self-insurance requirements. CalDIR
Green State Insurance can help businesses review Workers’ Compensation options based on their payroll, employee classifications, operations and claims history.
Explore Workers’ Compensation:
Green State Workers’ Compensation Insurance
2. General Liability Insurance
A Workers’ Compensation X-Mod relates to Workers’ Compensation and should not be confused with General Liability insurance.
Businesses—especially contractors—may separately need General Liability coverage because of their operations or contractual requirements.
General Liability can address certain third-party bodily injury and property damage exposures, subject to the terms, conditions and exclusions of the policy.
Explore General Liability:
Green State General Liability Insurance
3. Contractor Bonds
California contractors may also have bonding requirements separate from their Workers’ Compensation insurance.
A Workers’ Compensation policy does not replace a required contractor bond, and a contractor bond does not replace Workers’ Compensation insurance.
Explore Contractor Bonds:
Green State Contractor Bond Services
4. Builders Risk Insurance
Contractors involved in construction or renovation projects may also need to consider Builders Risk coverage for buildings and certain property during construction.
Again, this addresses a different exposure than Workers’ Compensation.
Explore Builders Risk:
Green State Builders Risk Insurance
High Mod Contractors May Face an Additional Problem
For contractors, a high X-Mod can create concerns beyond the insurance renewal itself.
Some projects, general contractors or contracting partners may have specific insurance, safety or qualification requirements.
That means the contractor may need to think about several issues at once:
Workers’ Comp coverage → X-Mod → COI requirements → contract requirements → project eligibility
This makes it important to review the actual project requirements rather than assuming that simply having an active insurance policy satisfies every contract.
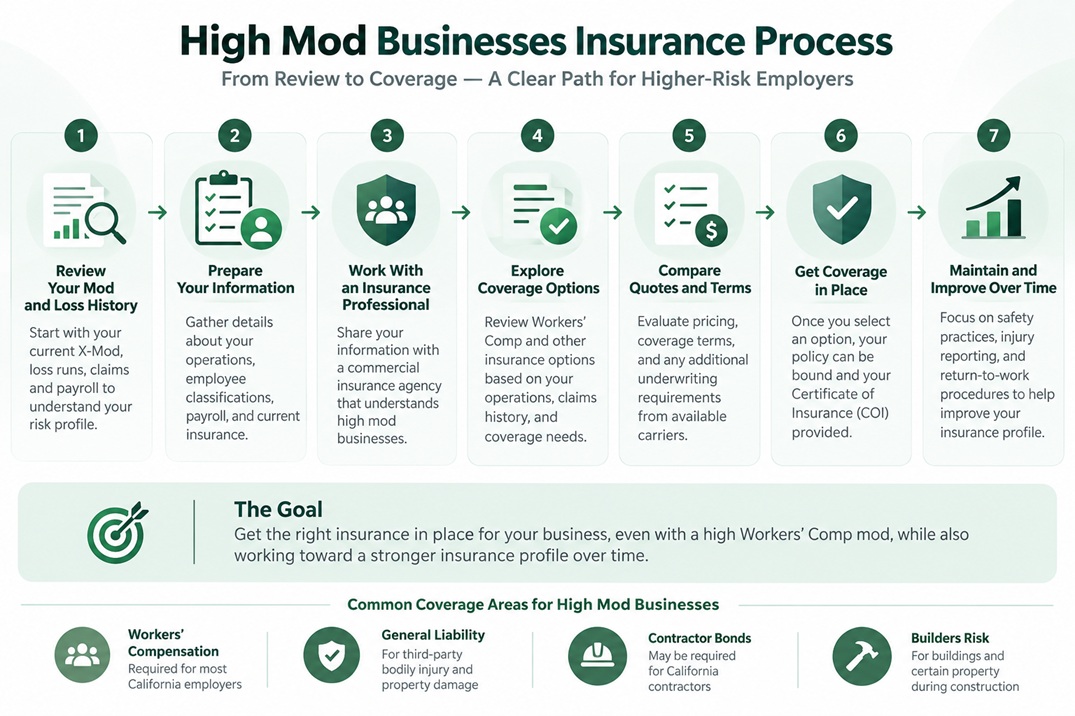
What Should You Prepare When Shopping for High Mod Business Insurance?
If your business has a high Experience Modification, preparing information before approaching the insurance market can help provide underwriters with a clearer picture of the risk.
Consider gathering:
| Information | Why It Helps |
|---|---|
| Current X-Mod | Shows the current experience rating |
| Experience Rating Worksheet | Helps review the information behind the X-Mod |
| Current Loss Runs | Shows claim history and status |
| Payroll | Important for Workers’ Comp rating |
| Employee Classifications | Helps describe employee job duties |
| Business Operations | Explains what the company actually does |
| Safety Program | Shows current risk-control procedures |
| Claim Explanations | Provides context around significant losses |
| Current Policy | Helps review existing coverage |
| Contract Requirements | Identifies required limits or documentation |
California policyholders can also request their current Experience Rating Worksheet from WCIRB. WCIRB
Don’t Ignore Open Workers’ Comp Claims
When reviewing insurance for high mod businesses, it can be useful to look beyond the X-Mod itself and review the claims contributing to the business’s loss history.
A loss run may contain both open and closed claims.
For open claims, businesses should work with their insurer, claims administrator and appropriate professionals to ensure current information is being communicated and legitimate claims are handled properly.
The goal should not be to improperly close claims merely to change an insurance number.
Instead, businesses should maintain accurate claim information and appropriate return-to-work and injury-management processes.
How Can a Business Improve Its Insurance Profile?
There is usually no instant method for changing an Experience Modification.
Because experience rating relies on historical payroll and loss information, improvements may take time to affect the data used in future ratings. WCIRB
However, businesses can work on factors within their control.
1. Review Your Experience Rating Worksheet
Check the data associated with your business and understand which information is contributing to the rating.
2. Review Loss Runs
Look at claim frequency, claim status and significant losses.
3. Verify Payroll and Classifications
Make sure business operations and employee duties are accurately described to your insurance professionals.
4. Strengthen Workplace Safety
Reducing future workplace injuries can improve the business’s long-term loss experience.
5. Improve Injury Reporting Procedures
Workplace injuries should be handled promptly and according to applicable Workers’ Compensation requirements.
6. Develop Return-to-Work Procedures
When medically appropriate, structured return-to-work processes can help employees transition back to work.
7. Review Your Insurance Before Renewal
Waiting until the final days before expiration can limit the amount of time available to gather underwriting information and review options.
High Mod Does Not Mean Uninsurable
This is one of the most important points for businesses searching for high mod businesses insurance.
A high X-Mod is an important underwriting factor, but it is not the complete story of a business.
A company may have experienced several claims in prior years and since made meaningful changes to its operations, safety procedures, management or workforce.
That context can matter when an insurance professional is preparing a submission for underwriting.
The objective is not to hide unfavorable history.
It is to present accurate information about both the historical losses and the business as it operates today.
How Green State Insurance Helps High Mod Businesses
Green State Insurance works with California businesses that need help reviewing commercial insurance options, including Workers’ Compensation.
For a business with a higher Experience Modification, the process can begin by reviewing:
- Your business operations
- Current Workers’ Compensation coverage
- Payroll and employee classifications
- X-Mod
- Loss runs
- Open and closed claims
- Insurance requirements
- Upcoming renewal date
From there, available coverage options can be reviewed based on the actual risk profile of the business.
The goal is not simply to look at the X-Mod number.
It is to understand the business behind it.
Looking for Insurance With a High Workers’ Comp Mod?
Having a high Experience Modification can make Workers’ Compensation insurance more complicated, but it does not mean you should assume there are no options.
Green State Insurance can help review your business, Workers’ Compensation history and coverage requirements to identify insurance options that may be available for your situation.
High Mod Workers’ Comp | Contractor Insurance | Commercial Insurance
Call Green State Insurance:
(949) 432-4805
View Green State Insurance Services
Frequently Asked Questions About High Mod Businesses Insurance
Common questions about high Workers’ Comp mods, X-Mod ratings, insurance options, and the information businesses should prepare before seeking coverage.
What is considered a high Workers’ Comp mod?
An Experience Modification should be interpreted within the applicable experience rating system and the employer’s circumstances. Rather than relying on a single generic cutoff, businesses should review their actual WCIRB Experience Rating Worksheet and the information used to calculate the X-Mod.
Can I get Workers’ Comp insurance with a high mod?
A high X-Mod does not automatically prevent a business from obtaining Workers’ Compensation insurance. Available carriers, pricing and underwriting requirements can depend on the business’s complete risk profile.
Why is my Workers’ Compensation mod high?
The answer depends on the data used in your experience rating. Claims and payroll information are important components of California’s experience rating system. Reviewing your Experience Rating Worksheet and loss history can help identify contributing factors.
Does a high mod affect General Liability insurance?
The Workers’ Compensation Experience Modification is part of Workers’ Compensation experience rating. General Liability is a separate coverage. However, insurers may separately evaluate claims, operations and other risk characteristics when underwriting other commercial policies.
Can I lower my X-Mod immediately?
Generally, businesses should not expect an immediate change simply from purchasing a new policy. California experience rating uses historical payroll and loss information, so changes in loss experience can take time to be reflected.
Where can I find my California X-Mod?
Qualifying California policyholders can obtain their current Experience Rating Worksheet, which contains their X-Mod, through
WCIRB
What information should I provide when looking for high mod businesses insurance?
Be prepared to provide information such as payroll, employee classifications, business operations, current coverage, X-Mod, loss runs and relevant claim information. Providing complete information can help insurers better understand the risk.
Have a High Workers’ Comp Mod?
Green State Insurance can help review your X-Mod, loss history, payroll, business operations, and Workers’ Compensation coverage options.