If you’re wondering why contractor insurance expensive , claim history is one of the first factors to review.
why contractor insurance expensive For most contractors, the answer comes down to a few specific risk factors — not simply because construction insurance is expensive by default.
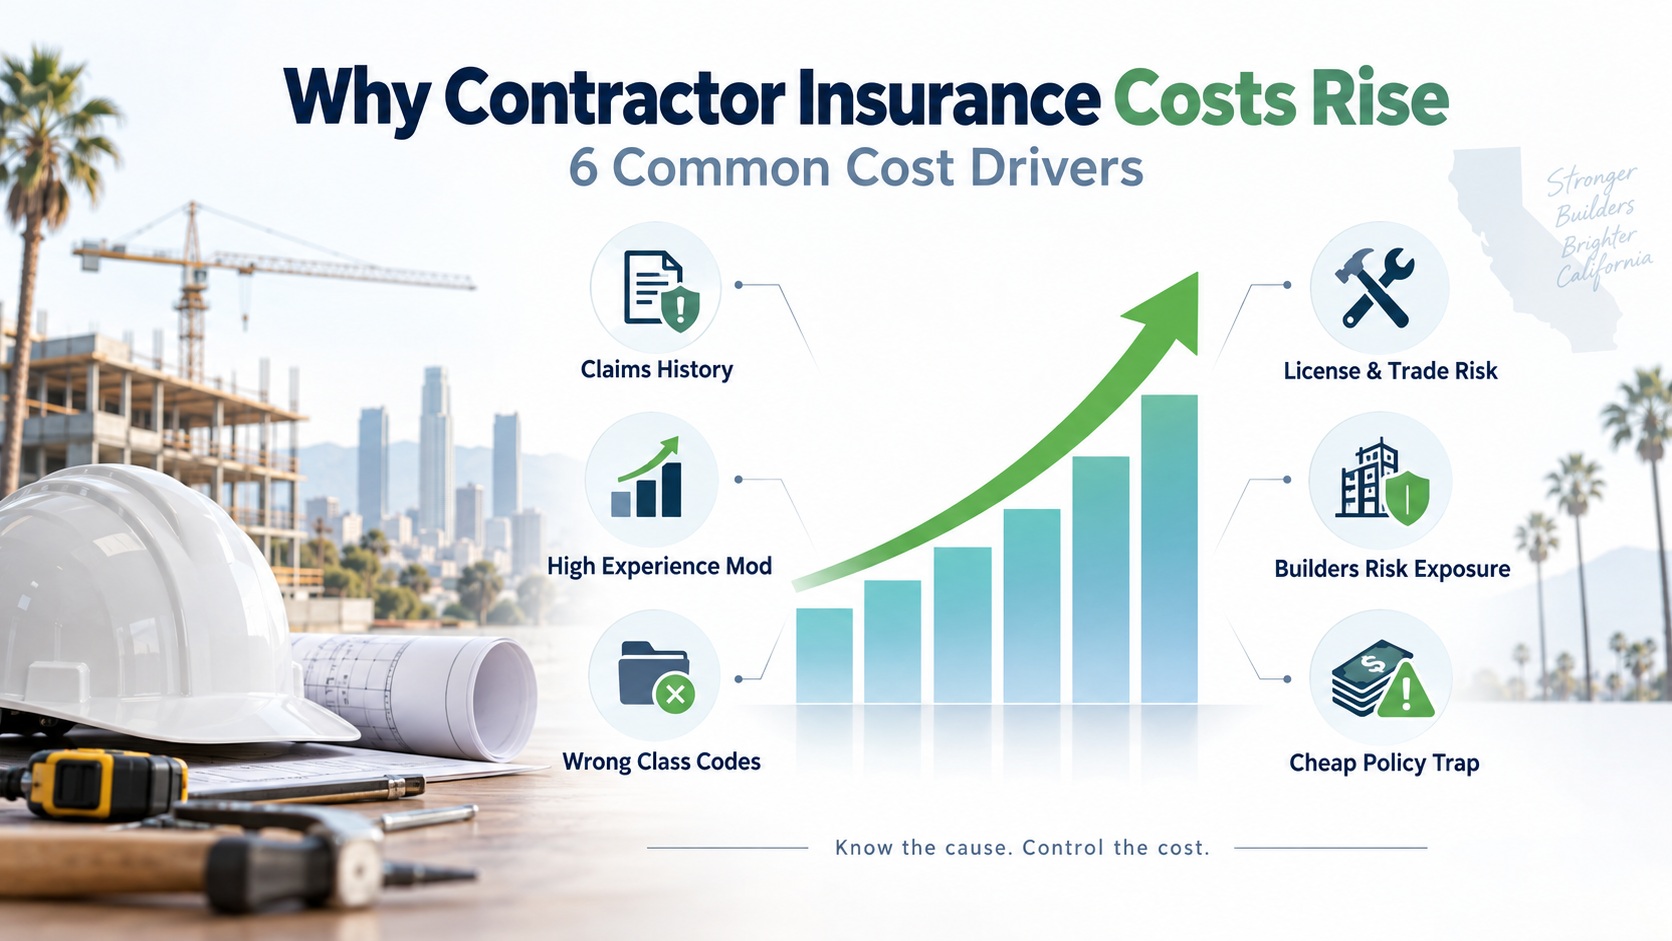
Previous claims, a high Experience Mod, incorrect job classifications, contractor license type, and project-specific risks can all push premiums higher.
Most California contractors assume high insurance costs are just part of doing business. But once you understand what insurers actually look at, you can often identify what is driving the cost and what may be improved.
This guide breaks down the main reasons contractor insurance costs rise in California and what contractors can do to keep those costs under better control.
Quick Summary: Why Contractor Insurance Costs Increase in California
| Factor | Why It Increases Insurance Costs | What Contractors Should Watch |
|---|---|---|
| Previous Claims | Claims history signals higher risk to insurers | Keep clear records, timelines, and corrective-action documentation |
| High Experience Mod | A Mod above 1.00 can increase Workers’ Comp premiums | Review claims, payroll, classifications, and safety practices |
| Incorrect Job Class Codes | Higher-risk classifications can raise premiums significantly | Make sure employees are classified based on the work they actually perform |
| License Type & Trade Risk | Different contractor trades carry different risk profiles | Keep insurance coverage aligned with the contractor license and actual operations |
| Project-Specific Exposure | Larger or longer projects may require additional protection | Consider Builders Risk coverage for materials, structures, and work in progress |
| Choosing the Cheapest Quote | Low-cost policies may include exclusions or higher renewal costs | Focus on stable, properly structured coverage rather than price alone |
According to the Workers’ Compensation Insurance Rating Bureau of California (WCIRB):
“An experience modification that is greater than 100 percent usually increases the cost of an employer’s workers’ compensation insurance premiums.”
— Workers’ Compensation Insurance Rating Bureau of California (WCIRB)
1. Previous Claims — Even When the Job Wasn’t Your Fault
One of the biggest reasons insurance premiums increase is claim history.
It doesn’t matter:
-
if the claim was small
-
if it’s already closed
-
or if the incident wasn’t your fault
From an insurer’s point of view, a claim is still a risk signal.
This applies to:
-
Workers’ Compensation claims
-
General Liability claims
-
On-site injuries or property damage
That’s why contractors with claims often see higher pricing on
Workers’ Compensation Insurance and
General Liability Insurance policies.
👉 Learn more about coverage options here:
-
Workers’ Comp: https://www.greenstateins.com/workers-compensation/
-
General Liability: https://www.greenstateins.com/general-liability/
How to limit the damage
Claims can’t be erased, but they can be explained.
Clear documentation, accurate timelines, and showing corrective action can significantly reduce how heavily a claim is weighted during underwriting.
2. High Experience Mod (High Mod) — A Silent Cost Multiplier
Your Experience Modification Rate (Mod) is one of the most important numbers insurers look at.
-
1.00 = average risk
-
Below 1.00 = safer than average
-
Above 1.00 = higher risk
Even a Mod of 1.10 or 1.20 can raise your workers’ comp premium far more than most contractors expect.
Why contractors end up with a high Mod
High Mods usually come from:
-
Repeated injuries
-
Poor claim follow-up
-
Incorrect payroll or job classification
-
Weak safety practices
Once your Mod increases, it affects every workers’ compensation quote you receive.
That’s why contractors with High Mods often struggle to find affordable
Workers’ Compensation coverage without proper guidance.
3. Incorrect Job Class Codes
This is one of the most common — and most expensive — mistakes.
If employees are placed under higher-risk job codes than the work they actually do, premiums can increase dramatically.
Examples:
-
Electrical work classified as general construction
-
Finish carpentry grouped with rough framing
A single incorrect class code can double your insurance cost without you realizing why.
This issue frequently impacts pricing across:
-
Workers’ Compensation
-
General Liability
-
Online Contractor Insurance applications
👉 Start with accurate coverage here:
https://www.greenstateins.com/contractor-insurance/
4. License Type and Trade Risk
Another reason why contractor insurance expensive in California is the type of work your license allows you to perform.
Insurance pricing in California is closely tied to your contractor license.
C-10 Electrical, C-5 Carpentry, C-6 Millwork, and General Contractors all carry different risk profiles. Insurance carriers often verify license details through CSLB to confirm accuracy.
When coverage doesn’t match your license:
-
Quotes get flagged
-
Rates increase
-
Or policies get declined altogether
This is especially important when bundling insurance with a
Contractor Bond for licensing or renewal.
👉 Contractor Bond details here:
https://www.greenstateins.com/contractors-bond/
5. Builders Risk and Project-Specific Exposure
Many contractors underestimate how much project-specific risk affects overall insurance pricing.
Large remodels, ground-up construction, or long-term projects often require
Builders Risk Insurance to protect materials, structures, and work in progress.
Without proper Builders Risk coverage:
-
General Liability exposure increases
-
Claims become more expensive
-
Future premiums go up
👉 Learn more about Builders Risk coverage in California:
https://www.greenstateins.com/builders-risk-insurance/
6. Chasing the Cheapest Quote
This is where many contractors get burned.
The cheapest policy often comes with:
-
Limited coverage
-
Strict exclusions
-
Sharp renewal increases
A policy that looks affordable today can become very expensive after one claim or renewal.
Smart contractors focus on stable, well-structured coverage, not just the lowest price.
That’s why many choose to start with a properly built
Online Contractor Insurance solution instead of jumping between carriers.
👉 Start here:
https://www.greenstateins.com/contractor-insurance/
The Bottom Line
So, why contractor insurance expensive ? In most cases, the cost reflects a combination of claims, classification, trade risk, and project exposure.
Contractor insurance in California is expensive — but it’s not random.
Costs rise because of:
-
Claims history
-
High Experience Mods
-
Incorrect class codes
-
License mismatches
-
Missing project-specific coverage
When these issues are handled correctly, even contractors with past claims or high-risk work can control their insurance costs.
Understanding why your insurance is expensive is the first step toward fixing it.